A Guide to Construction Plan Review for Insurance in CA
February 13, 2026 · 19 min read
Your new home is one of the biggest financial investments you'll ever make. Protecting that investment starts long before the first wall goes up—it starts with your blueprints. An uninsurable home is a massive liability, and carriers are now deciding what they will and won't cover based on the initial plans. A thorough construction plan review for insurance in California is your first line of defense in securing long-term protection. It ensures your design is not only compliant but also attractive to insurers. This article will guide you through the steps to get your plans approved, safeguarding your project's financial future from the very beginning.
Key Takeaways
- Build for Insurability, Not Just for Code: Your construction plans must meet the standards of both your local building department and your insurance carrier. Engage your insurer early to align your design and material choices with their requirements, ensuring your project is approved for coverage before you break ground.
- A Complete Submission Is a Fast Submission: The most common cause of delays is incomplete paperwork. Create a checklist of all required documents—from soil reports to safety plans—and review your submission for accuracy to ensure a smooth and efficient review process.
- Protect Your Policy from Common Pitfalls: Simple oversights can put your coverage at risk. Safeguard your project by carefully reading your policy's exclusions, correctly classifying all workers, and reporting any on-site incidents to your provider as soon as they happen.
How Does California's Construction Plan Review Work?
Getting your construction plans reviewed in California can feel like a complex process, but it breaks down into a few clear stages. Whether you're building a new home or doing a major renovation, your plans will be checked against state and local building codes to ensure they’re safe, compliant, and structurally sound. This official review is a critical step for getting your building permits, and it’s also something your insurance carrier will want to see. Understanding how this process works will help you prepare your documents, avoid delays, and show your insurer that you’re building a resilient, low-risk property.
Submitting Your Plans for Initial Review
Once you submit your project plans, the reviewing agency—like your local building department or a state body like HCAI—kicks off an initial check. Think of this as a quick triage to make sure your submission is complete. Within about a week, they’ll confirm they have everything they need and give you a rough timeline for the full review. It’s smart to submit foundational documents, like geotechnical or soil reports, well ahead of your main construction plans. This ensures the core review is based on approved site information, which can prevent major headaches later. The goal here is to start the official plan review process on the right foot with a complete package.
What to Expect After You Submit
After the detailed review, it’s common to get your plans back with comments and markups. Don’t panic—this is a normal part of the process. Reviewers will annotate your drawings to pinpoint any areas that don’t meet specific regulations, explaining what needs to be fixed. Your project will only get the final stamp of approval once every single comment has been addressed. This back-and-forth is designed to make your project safer and more compliant. Getting an independent review from a service like WiserBuild beforehand can help you catch many of these potential issues early, leading to a smoother and faster official approval.
Handling Corrections to Get Approved
When you receive requests for corrections, your next step is to revise the plans and resubmit them. Along with the updated drawings, you’ll need to include a written response that addresses each comment from the reviewer one by one. It’s important to be thorough and clear in your responses. Be mindful of deadlines, too. Most agencies have a timeframe for receiving your corrections, and if you don’t respond within that window (often 90 days), your project could be put on hold or even closed. Responding promptly and completely shows you’re on top of things and keeps your project moving toward that final approval.
Why Your Insurance Carrier Cares About Plan Reviews
When you look at your construction plans, you see a future home or a finished project. Your insurance carrier, on the other hand, sees a collection of risks they need to understand before they can agree to cover you. A construction plan review is their first and most important tool for assessing that risk. It’s not just about checking boxes; it’s about building confidence. Insurers want to partner with builders and homeowners who are proactive, detail-oriented, and committed to safety and compliance from day one.
Think of it this way: you’re asking an insurer to make a significant financial commitment to protect your project. In return, they need to see that you’ve done your homework. A thorough, professional plan review demonstrates that you’ve considered potential hazards, chosen appropriate materials, and are following established building codes. When your plans are clear, compliant, and resilient, you become a much more attractive client. This can lead to a smoother approval process, better policy terms, and the peace of mind that comes from knowing your project is insurable before you even break ground.
How Insurers Evaluate Risk and Liability
At its core, insurance is the business of managing risk. Construction insurance is designed to protect you, your contractors, and your investment from financial loss if something unexpected happens on-site. To do that effectively, the insurer first needs to understand what could go wrong. Your building plans are their primary source of information.
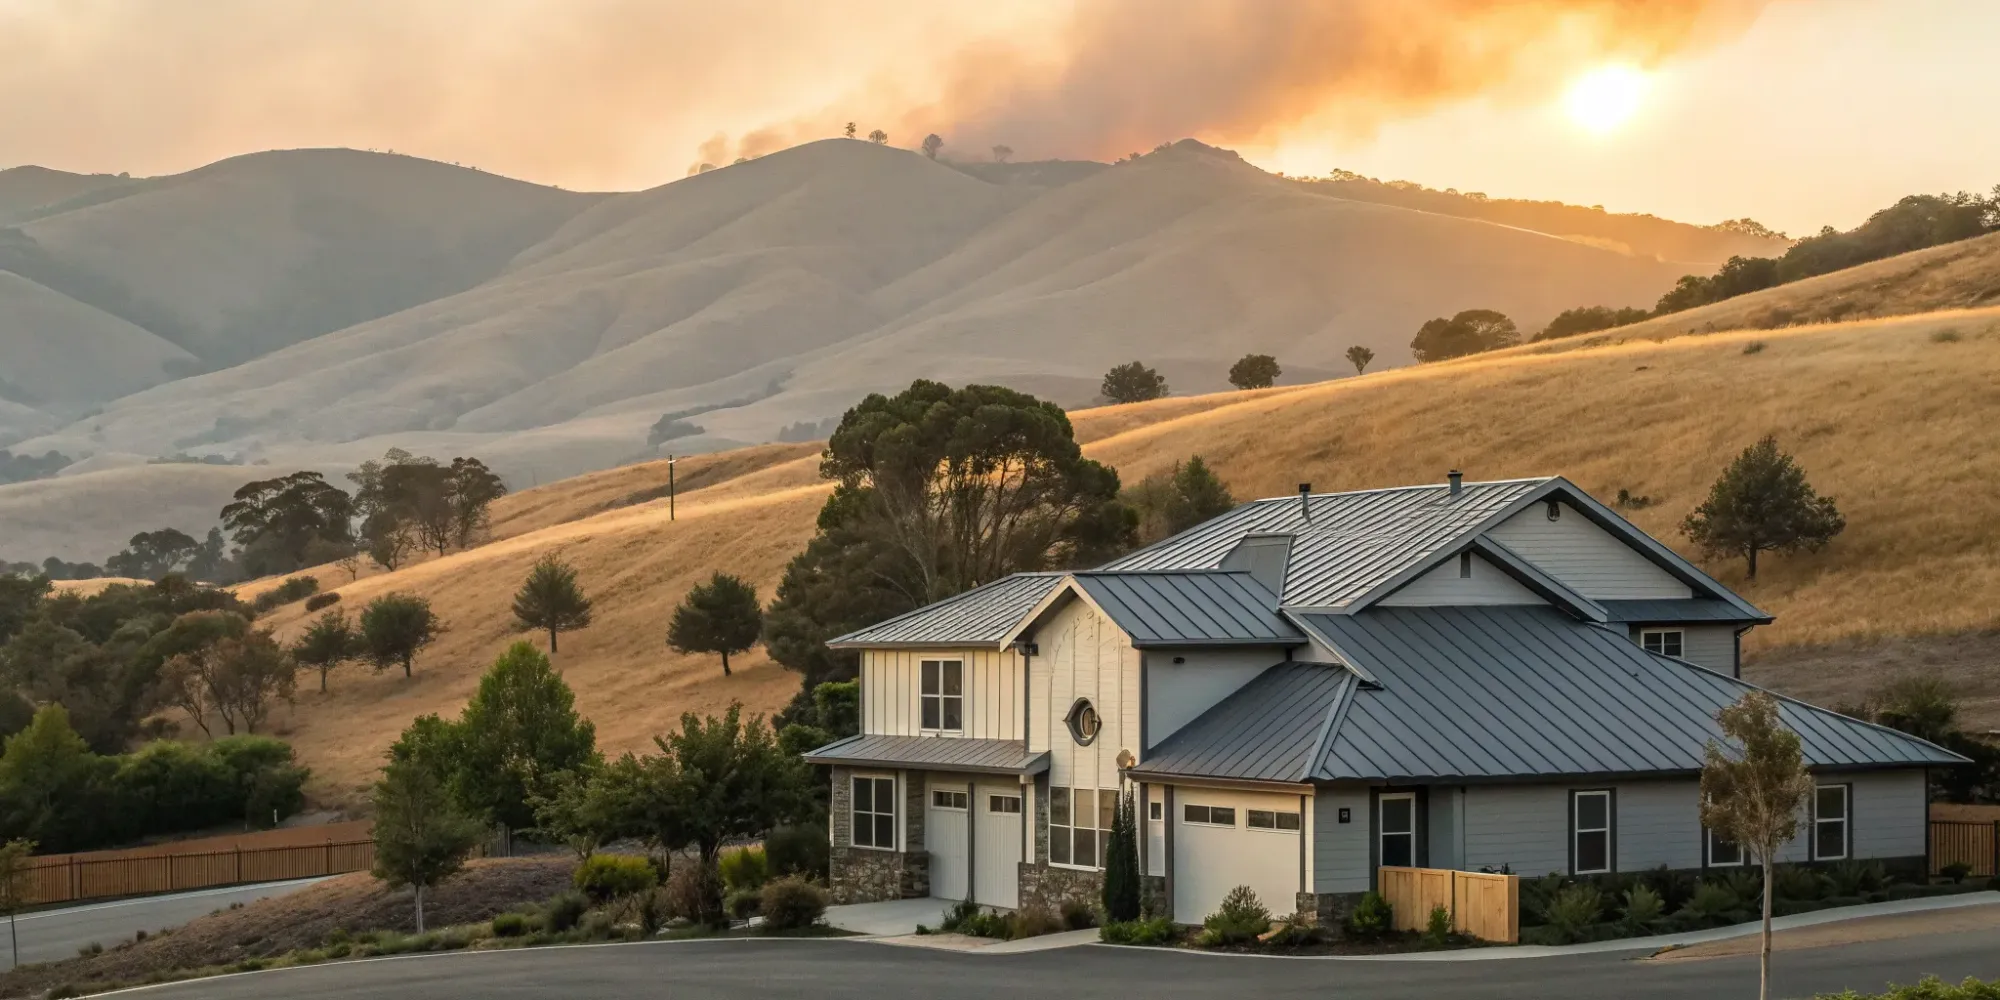
They’ll review your plans to see how you’re addressing specific risks relevant to your location. Are you building in a wildfire-prone area? They’ll look for fire-resistant roofing and siding. Is your site on a steep slope? They’ll check for retaining walls and proper drainage. A detailed plan that clearly outlines these mitigation strategies shows the insurer that you are a responsible partner, which can make securing coverage much easier.
Meeting Your Carrier's Compliance Rules
Insurance carriers operate under a strict set of rules, and they expect their clients to do the same. Before they issue a policy, they need proof that your project meets all relevant state and local codes, as well as their own internal standards. For many projects, especially public works, you can’t even begin without providing proof of liability insurance. For example, Caltrans requires contractors to get insurance pre-approval before a contract is even awarded.
A plan review serves as your formal proof of compliance. It’s a systematic way to demonstrate that your designs are up to code and meet the insurer’s requirements. By getting your plans reviewed early, you show that you’re a low-risk client who takes compliance seriously, which helps you avoid delays and last-minute issues.
The Link Between Permits and Policies
Getting a building permit and securing an insurance policy are two sides of the same coin. The rigorous planning and documentation required by your local building department are exactly what your insurance carrier wants to see. Both entities are focused on ensuring your project is safe, durable, and built to last. A plan that sails through the permit process is very likely to be viewed favorably by an insurer.
This goes beyond just the blueprints. A comprehensive plan also includes things like site-specific safety protocols and a realistic construction schedule. These elements show that you are prepared for the common challenges in construction and are committed to managing the project responsibly. When an insurer sees this level of foresight, they gain confidence that your project is less likely to result in costly claims.
What Documents Do You Need for a Plan Review in California?
Getting your construction plans reviewed can feel like you’re preparing for a final exam, but it’s really about showing your work. When you have all your documents in order, you’re telling reviewers and insurers that you’ve done your homework and are ready to build a safe, compliant, and resilient home. Think of it as assembling a complete file that proves your project is a smart investment for everyone involved. Each document tells a piece of the story, from the ground your home will stand on to the safety protocols that will protect your crew. Let’s walk through the essential paperwork you’ll need to gather for a smooth review process in California.
Geotechnical and Soil Reports
Before you can build up, you have to know what’s down below. Geotechnical and soil reports analyze the ground on your property, identifying its composition, stability, and any potential hazards like fault lines or liquefaction risk. In California, these reports are not just a good idea—they’re often required. State rules mandate that for many projects, you must submit geotechnical reports to ensure the foundation design is appropriate for the site conditions. This information is critical for your structural engineer and just as important for your insurance carrier, as it demonstrates you’re building a home on solid ground.
Proof of Insurance and Pre-Approval Forms
Insurers want to see that you’re already managing risk before the first nail is hammered. Providing proof of insurance and pre-approval forms shows that you’re prepared and responsible. This includes documents like your general liability policy and builder’s risk insurance. Some agencies, like Caltrans, even offer an Insurance Pre-Approval Program that lets contractors get their coverage verified before a project begins. Submitting these forms early in the review process gives your insurance carrier confidence that you have the right protections in place from day one, which can make the entire approval process much simpler.
Fire Resilience and Safety Documents
For anyone building in a high-risk area, this is one of the most important parts of your submission. These documents outline the specific measures you’re taking to protect your project from fire and other hazards. This goes beyond just listing fire-resistant materials; it includes a comprehensive site safety plan detailing evacuation routes, emergency contacts, and protocols for securing the site. Creating tailored safety plans for your specific location and build shows insurers that you are proactively addressing the real-world risks your property faces, making your project a much more attractive and insurable asset.
Structural Plans and Project Information
This is the heart of your submission package. Your structural plans include detailed blueprints, architectural drawings, material specifications, and engineering calculations that map out every aspect of your build. These documents need to be clear, complete, and compliant with all relevant building codes. But they do more than just kick off the project; they serve as the roadmap that keeps everything on track. Strong construction project planning is reflected in these documents, giving reviewers and insurers a clear picture of the final product and the steps you’ll take to get there safely and correctly.
What Insurance Do You Actually Need for a California Build?
Figuring out the right insurance for your construction project can feel like a puzzle, but it’s one of the most important steps to protect your investment. The right policies shield you from financial loss, liability, and unexpected setbacks. For a build in California, especially in a high-risk area, you’ll need a combination of coverages to ensure you’re protected from every angle, from the first day of excavation to the final walkthrough.
General Liability and Professional Indemnity
Think of general liability as your foundational safety net. This is the policy that covers you if your project accidentally causes bodily injury to someone or damages their property. It’s non-negotiable for any construction site, protecting you from the high costs of lawsuits and medical bills. For architects and designers, professional indemnity (or Errors & Omissions) insurance is just as critical. It covers claims related to mistakes in your plans or professional advice that result in financial loss for your client. Both are essential pieces of a comprehensive contractors insurance plan.
Builder's Risk and Property Coverage
While general liability protects you against claims from others, builder’s risk insurance protects the actual structure you’re building. Also known as "Course of Construction" insurance, this policy covers the building and your materials against damage from events like fire, theft, and vandalism during the construction phase. It’s designed to protect your direct financial investment in the project itself. Without it, a single unexpected event could force you to pay for rebuilding or replacing materials out of pocket, potentially derailing your entire project timeline and budget.
Workers' Compensation
If you have anyone working for you—even just one person—workers’ compensation is a must-have, and in California, it’s the law. This insurance covers medical expenses and lost wages for employees who get injured or become ill on the job. It’s not just about following the rules; it’s about taking care of your team and protecting your business from potentially devastating lawsuits. Having a solid workers' compensation policy in place is a critical part of protecting both your employees and your business from the financial fallout of a workplace accident.
Specialized Coverage for High-Risk Areas
Building in California often means dealing with unique risks like wildfires, earthquakes, or landslides. A standard insurance package might not cover these specific threats, leaving you exposed. This is where specialized coverage comes in. Depending on your location, you may need additional policies or riders for things like flood or environmental liability. Failing to secure the right protection is one of the most common and costly insurance pitfalls. Understanding the specific risks of your location and avoiding inadequate coverage is key to ensuring your project is truly secure.
How to Get Your Plans Approved by Your Insurer
Getting your building plans approved by your local jurisdiction is a huge milestone, but it’s only half the battle. You also need to get your insurance carrier on board. Insurers, especially in high-risk areas, are taking a much closer look at construction plans before they agree to provide coverage. They want to see that you’re building a home that’s not just up to code, but also resilient and insurable for the long haul. This isn't just another piece of paperwork; it's a critical step in protecting your investment.
Think of this as a pre-approval for your project’s risk. By showing your insurer that you’ve thoughtfully planned for potential hazards like wildfires or extreme weather, you’re demonstrating that you’re a responsible partner. This proactive step can make it easier to secure the right coverage at a better rate and prevents any nasty surprises down the road, like finding out your finished home is uninsurable. A project that an insurer has reviewed and feels confident in is one that’s set up for success from the very beginning. It’s about building with confidence, knowing that your investment is protected from the moment you break ground.
Know Your Insurer's Specific Rules
Every insurance carrier has its own set of rules and requirements, and they’re not always spelled out in big, bold letters. It’s easy to assume a standard policy will cover everything, but relying on generic forms can create serious gaps in coverage. Your insurer might have specific requirements for building materials in a wildfire-prone area or mandate certain structural designs in a region known for high winds.
Before you get too far into the design process, get a copy of your policy and read it carefully. Pay close attention to the sections on new construction, required endorsements, and exclusions. If the language is confusing, don't hesitate to ask your agent for clarification. Treating your policy as a key project document helps ensure your final plans align perfectly with what your insurer needs to see.
Prepare and Format Your Documents Correctly
When you submit your plans to an insurer, presentation matters. Disorganized or incomplete paperwork can lead to delays or even denials. One of the most frequent yet avoidable issues is simply failing to read the policy and understand what’s required. Insurers need to see that you’ve done your homework and are submitting a comprehensive, professional package.
Create a checklist of every document your insurer requires, from architectural drawings and structural calculations to soil reports and material specifications. Make sure everything is clearly labeled and formatted correctly. This is also the time to double-check that you’ve avoided common coverage mistakes, like misclassifying subcontractors or misunderstanding policy exclusions. A clean, complete submission shows you’re organized and serious, making the approval process much smoother.
Talk to Your Insurance Provider Early
Don’t wait until you have a problem to talk to your insurance provider. Your agent should be a key member of your project team from the very beginning. Opening a line of communication early allows you to get ahead of potential issues and build a positive relationship with your carrier. Delayed claim reporting can cause major headaches, and the same principle applies to the planning phase—late communication can lead to preventable problems.
Schedule a meeting with your agent once you have your preliminary designs. Walk them through your plans, explain your material choices, and ask for their feedback. This gives them a chance to flag any potential concerns before you’ve invested too much time and money. It also shows them that you value their expertise and are committed to managing risk proactively.
Work with a Compliance Professional
Let’s be honest: building codes and insurance policies are complex. It’s a lot to expect architects, builders, or homeowners to be experts in every nuance. This is where a compliance professional can be invaluable. They specialize in the intricate details of construction compliance and insurability, acting as a bridge between your design team and your insurance carrier.
A professional can review your plans specifically through the lens of an insurance underwriter, spotting potential red flags you might have missed. They can help you with assessing their specific coverage needs and ensuring your documentation is flawless. Working with an expert not only saves you time and reduces stress but also gives your insurer the confidence that your project has been thoroughly vetted for risk, making a smooth approval far more likely.
Common Mistakes That Jeopardize Insurance Coverage
Getting your construction project insured is a huge milestone, but it’s not a "set it and forget it" task. The path from groundbreaking to final inspection is filled with potential pitfalls that can put your coverage at risk. Even small, unintentional errors can lead to denied claims, leaving you financially exposed when you need protection the most. Think of your insurance policy as a partnership—it requires you to hold up your end of the bargain by following procedures and maintaining clear communication.
Understanding the common slip-ups can help you stay on the right track. These aren't complex legal loopholes; they're often simple administrative oversights or misunderstandings that can have major consequences. From misplaced paperwork to reporting delays, being aware of these issues is the first step toward avoiding them. Let’s walk through some of the most frequent mistakes so you can ensure your project remains protected from start to finish.
Incomplete Submissions and Missing Paperwork
It sounds almost too simple, but incomplete or missing paperwork is one of the fastest ways to get a claim denied. When you’re juggling contractors, timelines, and budgets, it’s easy to rush through forms or forget to attach a required document. Insurers require thorough documentation to assess risk and process claims correctly. A failure to read and understand the policies often leads to these kinds of errors. Before you submit anything, create a checklist of all required documents. Double-check that every form is filled out completely and accurately. A few extra minutes of review can save you from major headaches and delays down the road.
Misunderstanding Policy Exclusions
Every insurance policy has exclusions—specific situations, perils, or types of damage that it won't cover. Many builders and homeowners get into trouble by assuming their policy is a catch-all safety net. For example, a standard builder's risk policy might not cover flood damage or issues arising from faulty workmanship. According to Apex Risk, misunderstanding policy exclusions can create serious gaps in your protection. The best way to avoid this is to read the exclusions section of your policy carefully. If the language is confusing, ask your insurance agent to explain it in plain English. Be proactive and ask "what if" questions related to your project's specific risks.
Incorrectly Classifying Workers
How you classify the people working on your site has significant insurance implications. Misclassifying an employee as an independent contractor (or vice-versa) can lead to major problems, especially with workers' compensation and general liability coverage. If someone you’ve classified as a subcontractor gets injured on the job and they don't have their own insurance, the liability could fall back on you. Your insurer might deny the claim if they determine the worker was incorrectly classified. Make sure you understand the legal definitions in your state and require all true subcontractors to provide proof of their own insurance before they start work.
Reporting Claims or Issues Too Late
When an incident occurs on your construction site, time is of the essence. Most insurance policies include a clause that requires you to report any potential claim in a timely manner. Waiting to see if a small problem gets worse or hoping it will resolve itself is a risky move. As legal experts at Stoel Rives note, delayed claim reporting is a critical mistake that can give your insurer grounds to deny coverage. Report any accident, damage, or potential issue to your provider as soon as it happens. It’s always better to over-communicate and have the incident on record, even if it doesn’t end up turning into a formal claim.
Best Practices for a Smooth Plan Review
Getting your construction plans reviewed and approved by an insurer doesn’t have to be a bottleneck. With a bit of foresight and organization, you can make the process straightforward for everyone involved. It’s all about clear communication, smart planning, and using the right tools to keep everything on track. Adopting these practices not only speeds up approvals but also builds a stronger, more resilient project from the ground up.
Communicate Proactively with Reviewers
Clear and consistent communication is your best tool for avoiding delays. Make sure your entire team, from the field to the office, is on the same page. When your reviewer has a question, a prompt and clear answer can prevent a minor query from turning into a major hold-up. Creating a central hub that connects your teams ensures everyone is working with real-time data and can respond quickly. Don’t wait for reviewers to chase you down for information; provide regular updates and make it easy for them to find the documents and details they need.
Assess Risk Throughout the Project
In an area with risks like wildfires, your initial plan is just the starting point. Conditions can change, and your project needs to adapt. Strong project planning involves assessing risk not just once, but continuously. Managing your construction plan dynamically is a strategic advantage that shows your insurance carrier you’re serious about mitigating potential issues. Schedule regular check-ins to review material choices, site conditions, and compliance with the latest safety codes. This ongoing diligence makes your project more insurable and resilient in the long run.
Use Technology to Stay Organized
Keeping track of blueprints, permits, compliance forms, and communication logs can feel overwhelming. This is where technology can be a game-changer. Using project management software helps teams stay organized, track revisions, and maintain a clear record of every decision. For an insurance review, this is invaluable. A well-organized digital file with version control and clear documentation shows professionalism and makes it easy for the reviewer to confirm that all requirements have been met, leading to a faster approval.
Plan Ahead for Potential Delays
Every construction project has a timeline, but experienced builders know that sticking to it requires planning for the unexpected. Delays happen, whether from supply chain issues, weather, or feedback from a plan review. Instead of hoping for the best, build buffer time directly into your project schedule. When you anticipate potential hurdles and build them into your plan, you’re better prepared to handle them without derailing the entire project. This foresight demonstrates to your insurer that you are managing the project responsibly.
Get Your Plans Ready for Review
Getting your construction plans reviewed can feel like a huge hurdle, but a little preparation makes the process much smoother for you, your builder, and your insurer. By thinking ahead, you can avoid common delays and get the green light to start building sooner. Here are a few key steps to get your plans in top shape for review.
Give Yourself Plenty of Time
It’s tempting to wait until the last minute, but submitting your plans well before your main construction timeline is one of the best things you can do. Early submissions give reviewers the time they need to be thorough, especially when dealing with complex site information for homes in high-risk areas. California's official plan review processes note that detailed reports require significant attention, so sending them in early prevents a bottleneck later on. This buffer allows you to address any initial feedback without derailing your entire project schedule.
Make Sure Your Submission is Complete
A common reason for delays is an incomplete submission package. Before you send anything off, double-check that you have all the required documents and that they’re formatted correctly. Think of it like packing for a trip—you don’t want to realize you’ve forgotten something important after you’ve already left. If your submission is missing information, it will likely be returned for corrections, which unfortunately pushes back your approval date. Taking an extra hour to ensure everything is in order can save you weeks of waiting.
Understand Your Estimated Timeline
To help you plan, reviewers often provide an Anticipated Date of Plan Approval (APAD). This isn’t a firm deadline but an estimate based on how long it has taken to review similar projects in the past. Knowing this date helps you set realistic expectations for your construction timeline and communicate clearly with your contractors and insurer. It gives everyone a shared goal to work toward and helps you manage the moving parts of your project without guessing when you’ll get your approval.
Be Prepared for Feedback and Corrections
It’s completely normal for plans to come back with notes and required corrections. This feedback isn’t a sign of failure; it’s part of the collaborative process to ensure your home is safe, compliant, and insurable. When the reviewer identifies issues, they will be marked directly on your plans. Your job is to work with your architect or builder to address these points and resubmit the corrected documents. Being ready for this step and responding quickly will keep your project moving forward toward final approval.
Related Articles
- A Guide to Building Plan Reviews for Insurability in CA
- 5 Best Insurance for New Homes in California
- What Are Insurance Compliant Building Plans?
Frequently Asked Questions
Why does my insurance company need to see my plans if the city is already reviewing them? This is a great question because it gets to the heart of why both reviews matter. Your local building department is focused on code compliance—they’re making sure your project meets the minimum safety and structural standards required by law. Your insurance carrier, on the other hand, is looking at your project through the lens of long-term risk. They want to see that you’re not just meeting the minimums, but that you’re building a resilient, durable home that will be less likely to result in a major claim down the road.
Is it a bad sign if my plans come back with a lot of comments and corrections? Not at all. In fact, you should expect it. Think of the review process less like a final exam and more like a collaboration. The reviewer’s job is to catch potential issues before they become expensive problems on a construction site. Getting feedback and markups is a standard part of refining your plans to make them safer, more compliant, and ultimately, more insurable. A thorough review with detailed comments shows the process is working as it should.
Do I really need to talk to my insurance agent before my plans are even finished? Yes, and the earlier, the better. Don’t wait until your plans are finalized to bring your insurance agent into the loop. Sharing your preliminary designs gives them a chance to flag any potential issues with materials or building methods that might make your project difficult or expensive to insure. A quick conversation early on can save you from having to make costly changes later and shows your insurer that you’re a proactive and responsible partner.
My project is just a small renovation. Do I still need to worry about things like soil reports and fire safety documents? The need for specific documents is often determined by your location’s risk level, not just the size of your project. If you’re building in a designated high-risk area for wildfires or earthquakes, even a smaller addition will likely need to meet stringent safety and material requirements. These documents prove to both the building department and your insurer that your project is designed to withstand the specific threats of your environment, protecting your entire investment.
What's the one thing I can do to make the insurance approval process go faster? The single most effective thing you can do is submit a complete and well-organized package from the very beginning. Disorganized or incomplete submissions are the number one cause of delays. Before you send anything, create a checklist of every required document, from structural plans to proof of insurance, and make sure every form is filled out correctly. A clean, professional submission makes the reviewer’s job easier and signals that you’re a client who is serious about getting things right.